Character Homes vs. New Construction in Dr. Phillips: 2026 ROI Guide
⚡ Quick Summary: Character Homes vs. New Construction
- The Architectural Divide: Established Dr. Phillips real estate offers mature half-acre lots and established tree canopies in enclaves like Bay Hill and Sand Lake Hills. Modern new construction delivers single-story aging-in-place floor plans, 10-to-12-foot ceilings, and turnkey efficiency on more compact zero-lot-line footprints.
- The Renovation Reality: Executing a full gut-renovation on an older custom home currently averages $200 to $250+ per square foot in Central Florida. Factoring in contractor timelines, permitting delays, and carrying costs, right-sizers frequently achieve higher net ROI by capturing existing equity and buying turnkey.
- The Insurance Dividend: Post-2020 construction built to current Florida Building Codes qualifies for maximum discounts on the state-certified Wind Mitigation Inspection (Form OIR-B1-1802), reducing annual hazard insurance premiums by 30% to 50% ($4,000–$7,000/yr savings) compared to 1980s–1990s builds facing strict 15-year roof underwriting cutoffs under F.S. 627.7011.
When high-equity homeowners decide to right-size in Dr. Phillips, they inevitably encounter a critical crossroads: do you purchase a vintage custom estate on a spacious, mature lot, or do you transition into a modern turnkey build?
In helping clients navigate acquisitions and rightsizing moves across Southwest Orange County via The Diplomatic Advantage, the question is rarely about architectural charm alone. It comes down to capital expenditure risk, insurance feasibility, and long-term carrying cost drag. Below is the operational framework to weigh an older estate against a modern build before you submit an offer.
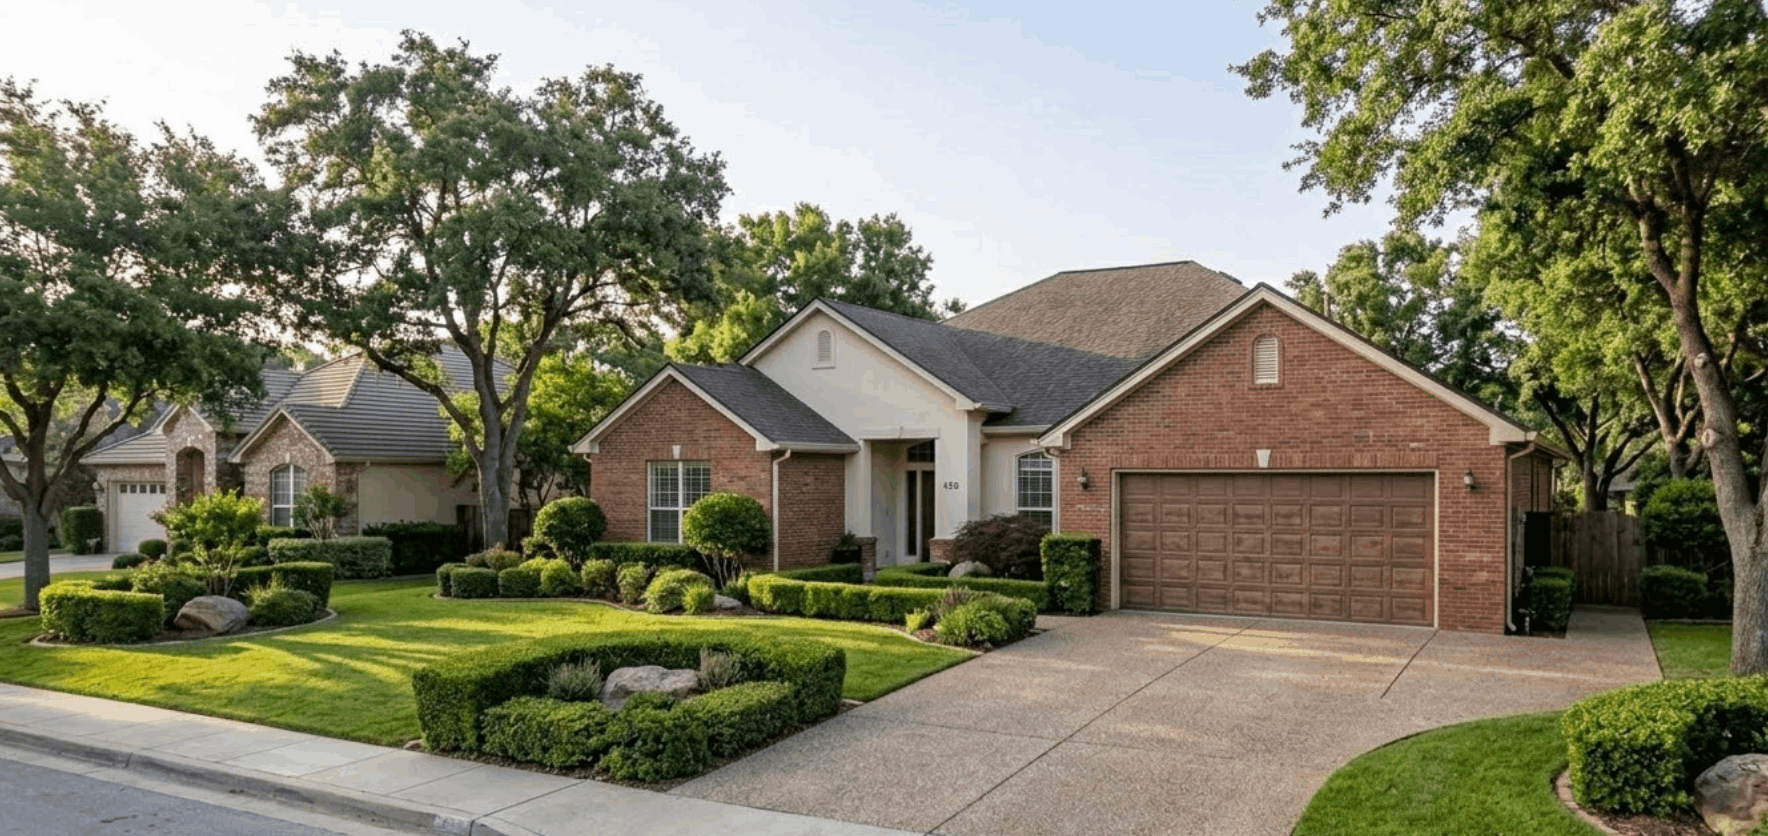
1980s–1990s Character Estates vs. 2020+ Turnkey Construction
| Property Dimension | 1980s–1990s Character Estate | 2020+ Turnkey Construction |
|---|---|---|
| Lot Profiles & Setting | 0.33 to 0.75+ acres, mature oak canopies, expansive setbacks | 0.15 to 0.25 acres, compact footprints, zero-lot-line options |
| Floor Plan Layout | Segmented formal rooms, sunken living areas, multi-story layouts | Open-concept sightlines, 10–12 ft ceilings, single-story master wings |
| 4-Point Inspection Risk | High (Aging roofs, copper/polybutylene piping, older electrical panels) | Zero (Modern PEX plumbing, 200-amp panels, current building codes) |
| Hazard Insurance Baseline | $9,000 – $14,000+ / yr (Strict 15-yr roof cutoff) | $3,500 – $5,500 / yr (Full wind mitigation discounts) |
| Upfront Capital Demand | Lower entry price, but requires $150k–$300k+ in renovation capital | Higher initial price per square foot, but immediate move-in readiness |
| Market Resale Velocity | 60 – 120+ Days on Market if unrenovated | 20 – 45 Days on Market (High demand for turnkey product) |
The $250/Sq. Ft. Renovation Trap in Older Estates
Buyers looking at homes in established subdivisions like Bay Hill or Sand Lake Hills often imagine doing a "light cosmetic refresh." However, once construction begins, upgrading 1980s and 1990s builds to modern luxury expectations involves significant hidden costs:
- Structural Wall Removal: Modern open-concept kitchen-to-family-room configurations require engineered steel support beams and foundation footings.
- Plumbing & Electrical Overhauls: Homes built in the late 1980s or 1990s often feature cast-iron under-slab drain lines or outdated electrical panels that private insurance carriers reject during a 4-Point inspection.
- Permitting & HOA Approvals: Orange County building permits and strict subdivision Architectural Review Committees (ARCs) can extend construction timelines by 6 to 12 months.
The Remodeling Math vs. Turnkey Equity
A comprehensive gut-renovation of a 4,000 sq. ft. home at $200–$250/sq. ft. adds $800,000 to $1,000,000 in cash outlay on top of your acquisition price, plus 9 to 14 months of temporary living costs. For right-sizers, allocating that capital into a newer construction single-story villa in communities like Dellagio or Vizcaya provides immediate lifestyle freedom without renovation management friction. Review our complete Downsizing vs. Right-Sizing ROI Model.
Florida Insurance Underwriting & The 15-Year Roof Hurdle
In Florida’s insurance market, property age directly impacts your bottom line. Under Florida Statute 627.7011, admitted carriers cannot deny policy renewals solely for roofs under 15 years old that have remaining useful life. However, once an asphalt shingle roof passes 15 years, private insurance carriers frequently decline new coverage on purchase transactions.
Furthermore, older estates lack modern storm-hardening features. In contrast, homes built after 2018 conform to updated Florida Building Codes, featuring:
- Secondary Water Resistance (SWR): Self-adhering polymer-modified bitumen underlayment that seals roof decking seams against wind-driven rain.
- Hurricane Clips & Straps: Engineered metal connectors tying rafters directly into concrete tie-beams for maximum uplift resistance.
- Impact-Rated Windows & Doors: Eliminates the need for hurricane shutters while earning maximum insurance credits on Form OIR-B1-1802.
This structural compliance unlocks an immediate $4,000 to $7,000 annual insurance savings. Understand how structural liabilities impact holding overhead in our audit of The Cost of Staying in a Large Orlando Home.
CDD Fees and HOA Structures: Older vs. Newer Developments
A major structural advantage of Dr. Phillips is that established neighborhoods (Bay Hill, Phillips Landing, Turtle Creek) carry $0 in Community Development District (CDD) bond debt. However, buyers exploring newer infill construction must verify parcel tax bills carefully.
Some newer master-planned communities in adjacent corridors (such as Horizon West or Lake Nona) finance infrastructure through 30-year non-ad valorem municipal bonds that add $2,000 to $4,500+ per year to your tax bill. In Dr. Phillips, newer enclaves like Phillips Grove or luxury townhomes in Dellagio offer modern construction while maintaining standard HOA frameworks. Review our neighborhood-level breakdown in CDD Taxes vs. HOA Fees Explained.
Resale Velocity and Buyer Demand Patterns
When it comes time to liquidate or right-size in the future, modern turnkey properties command faster market velocity. The qualified buyer pool for luxury homes in Central Florida overwhelmingly favors move-in-ready product with single-story master suites, low utility bills, and low maintenance burdens.
While an unrenovated 1990s estate may linger for 90 to 120+ days awaiting a buyer willing to manage extensive remodeling, updated turnkey villas clear in 30 to 45 days. Examine market turnover patterns in our report on How Long It Takes to Sell a Luxury Home in Orlando.
Which Property Type Fits Your Strategy?
Choose a Character Estate If:
You prioritize half-acre or larger lot footprints, expansive privacy buffers, mature oak canopies, golf cart access in Bay Hill, and have the capital reserves to execute a phased custom modernization.
Choose New Construction If:
You prioritize a lock-and-leave lifestyle, low hazard insurance carrying costs, single-story open floor plans, modern energy efficiency, and immediate turnkey move-in readiness with zero remodeling delays.
Browse active inventory across both categories in our Dr. Phillips property search, explore luxury estates in Windermere, or review our client experiences in our verified testimonials.
Evaluate Character vs. New Build ROI Before You Offer
Weighing an older estate against a modern build in Dr. Phillips? Connect with Yousef Zeidan for an address-specific 4-Point inspection risk audit, renovation cost-benefit modeling, and access to off-market inventory.
Private Tax-Sensitive Relocation Strategy
Frequently Asked Questions
Is it better to buy a character home or new construction when downsizing in Dr. Phillips?
It depends on your maintenance tolerance and lifestyle goals. Character estates in Bay Hill or Sand Lake Hills offer mature landscaping and half-acre lots, but frequently demand $150k–$300k+ in structural updates. Modern construction provides turnkey efficiency, single-story layouts, and 30% to 50% lower hazard insurance carrying costs.
How much does it cost to renovate an older home in Dr. Phillips?
Comprehensive gut-renovations in the Southwest Orlando luxury market currently average between $200 and $250+ per square foot. High-end kitchen transformations and master suite reconfigurations can easily scale from $150,000 to over $400,000 depending on structural wall removal and plumbing relocation.
How do roof age rules under Florida Statute 627.7011 affect home purchases?
Under Florida Statute 627.7011, insurers cannot decline renewal solely because a roof is under 15 years old with remaining life. However, on purchase transactions, voluntary insurance carriers frequently refuse new policies on asphalt shingle roofs over 15 years, requiring buyers to negotiate a replacement or seek Citizens Property Insurance.
What insurance discounts apply to newer construction in Central Florida?
Homes constructed after 2018 qualify for maximum wind-mitigation credits on Form OIR-B1-1802. Features such as secondary water barriers, hurricane clips, impact-rated openings, and hip-roof architecture lower annual hazard premiums from $10,000–$14,000+ down to $3,500–$5,500/year.
Do newer homes maintain higher resale liquidity in Dr. Phillips?
Yes. Modern open-concept floor plans, energy-efficient mechanicals, and single-story configurations appeal to a broader segment of affluent buyers, resulting in lower average days on market (30–45 days) compared to unrenovated vintage estates (90–120+ days).
Yousef Zeidan
Luxury Right-Sizing, Downsizing, and Tax-Sensitive Relocation Specialist
Specializing in luxury right-sizing, downsizing, and tax-sensitive relocation across Dr. Phillips, Windermere, and the Butler Chain of Lakes.
- Brokerage: RE/MAX Prime Properties
- License ID: SL3520428
- Phone: +1 (917) 743-8865
- Email: yousef@floridalistings.io
- Office Address: 311 South Main Street, Winter Garden, FL 34787, USA
Categories
Recent Posts


Request Your Confidential Risk Audit