Is It Time to Downsize in Orlando? Net Equity & Cost Guide (2026)
⚡ Quick Summary: Orlando Downsizing & Equity Strategy
- The Core Catalyst: Downsizing in Central Florida is fundamentally an exercise in capital reallocation. Homeowners in Dr. Phillips, Windermere, and Winter Park unlock trapped equity while eliminating high maintenance overhead, aging roof risks, and daily traffic gridlock along I-4 and SR-417.
- The Carrying Cost Shift: Transitioning from a 5,000+ sq. ft. legacy estate into a modern luxury villa or townhome routinely cuts all-in carrying costs (property taxes, insurance, routine mechanical repairs, and landscaping) by $25,000 to $40,000+ per year.
- The Statutory Safeguard: Homeowners can transfer up to $500,000 in accumulated tax assessment differential to their next primary residence using Florida's Save Our Homes Portability (Form DR-501T), preventing an abrupt jump to current market ad valorem valuations.
Downsizing is not merely a retirement checklist item—it is an executive financial decision. Across Southwest and Central Orlando, high-equity homeowners in their 40s, 50s, and 60s are right-sizing their real estate portfolios to eliminate administrative drag and unlock liquid capital. When a 5,000-square-foot estate no longer serves your daily routine, continuing to carry its operational overhead represents unnecessary friction.
Navigating this move in Central Florida requires looking beyond national advice. State-specific factors—including CDD and HOA fee structures, Florida's complex property insurance market under F.S. 627.7011, and Save Our Homes tax portability—dictate whether a move preserves wealth or simply trades one expense for another.
Key Signals It Is Time to Right-Size Your Orlando Residence
The clearest sign is a persistent imbalance between what your property demands in capital and what your household actually utilizes. In our advisory practice across Dr. Phillips and Windermere, four indicators suggest it is time to model a transition:
- Unused Square Footage: Paying heating, cooling, hazard insurance, and county taxes on 2,000+ square feet of guest suites, secondary living rooms, and bonus spaces that sit empty for months.
- Escalating Florida Insurance & Maintenance: Florida property insurance carriers heavily penalize roofs approaching or exceeding the 15-year mark under F.S. 627.7011. Maintaining aging swimming pools, multi-zone HVACs, and expansive landscaping often demands 8 to 12 hours of management weekly. Review our breakdown in The True Cost of Staying in a Large Orlando Home.
- Peak Commuter Congestion: Rush-hour bottlenecks on I-4 (Sand Lake to Downtown) and SR-417 (Lake Nona corridor) consume hours each week. Moving closer to primary business hubs reclaims valuable personal time.
- Illiquid Balance Sheets: Homeowners who acquired properties between 2012 and 2020 often hold $800,000 to $2,000,000+ in illiquid equity. Selling unlocks this capital to purchase a right-sized luxury home outright while diversifying into liquid, yielding assets.
Legacy Estate vs. Right-Sized Luxury Asset: Annual Carrying Cost Model
Downsizing reduces some operating costs while shifting others. The model below outlines the financial shift when transitioning from an older 5,200 sq. ft. custom estate into a modern 2,800 sq. ft. luxury single-story villa in Southwest Orlando:
| Financial & Operating Line Item | Legacy Estate ($2.5M Valuation) | Right-Sized Villa ($1.4M Valuation) | Annual Net Difference |
|---|---|---|---|
| Ad Valorem Taxes (with $500k Portability) | $28,500 / yr | $14,200 / yr | +$14,300 Savings |
| HOA Dues & Maintenance Reserves | $18,000 / yr (Owner-managed upkeep) | $6,200 / yr (HOA-included lawn/pool) | +$11,800 Savings |
| Homeowners Hazard & Wind Insurance | $14,500 / yr (Aging roof, older codes) | $5,800 / yr (Newer construction codes) | +$8,700 Savings |
| Electric, Water & Irrigation Utilities | $9,600 / yr | $4,200 / yr | +$5,400 Savings |
| Total Annual Operating Expense | $70,600 / yr | $30,400 / yr | +$40,200 / yr Net Savings |
Learn more about structuring your specific numbers in our cornerstone Orlando Downsizing and Rightsizing Guide.
Comparing Orlando Housing Types for Downsizers
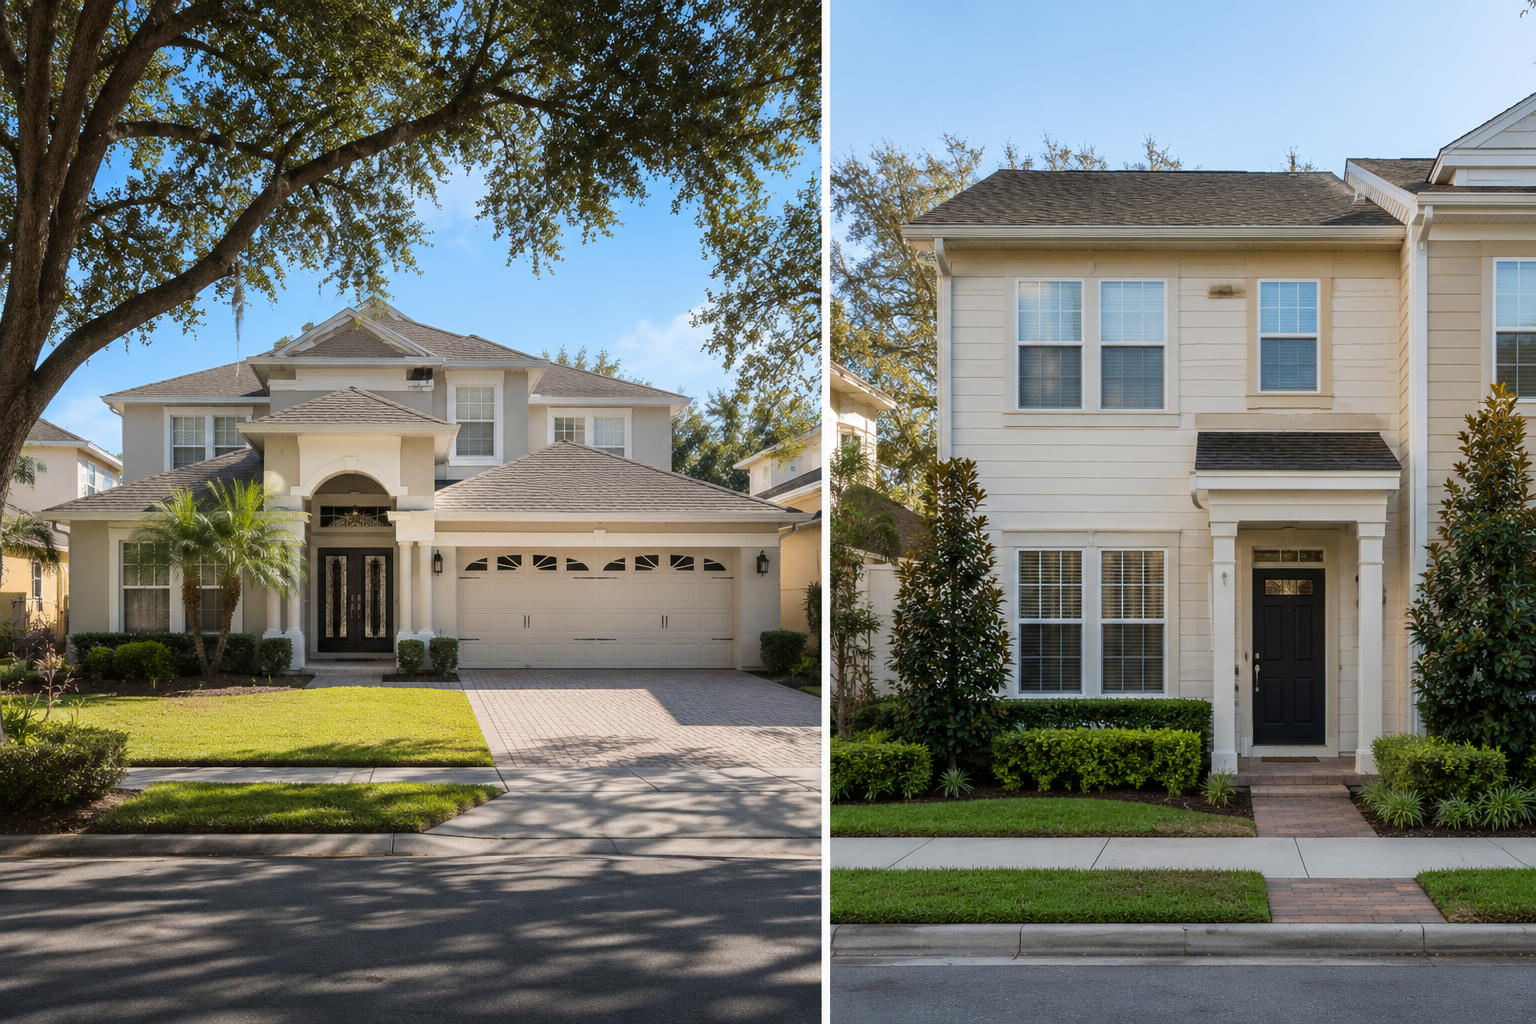
Choosing the right property type involves balancing maintenance freedom against privacy and association control. The matrix below outlines how the three most popular downsizing options compare in Central Florida:
| Housing Category | Typical Monthly HOA | Maintenance Burden | Optimal Buyer Profile |
|---|---|---|---|
| Luxury Townhome / Villa | $250 – $500 / mo | Low (Exterior grounds & roof covered) | Lock-and-leave professionals and seasonal residents seeking zero exterior yard upkeep. |
| Single-Story Executive Home | $0 – $200 / mo | Moderate (Owner maintains private lot) | Downsizers eliminating stairs while retaining private yards, three-car garages, and HOA flexibility. |
| Active Adult (55+) Enclave | $350 – $650 / mo | Low (Full clubhouse & landscape care) | Buyers seeking peer social amenities, though future resale is restricted to age-qualified purchasers. |
Submarket Selection: Where to Target in Central Florida
- Dr. Phillips & Sand Lake Road: Ideal for downsizers who want fine-dining access along Restaurant Row, low county millage (~16.2 mills), and zero CDD debt. See active listings in Dr. Phillips homes for sale.
- Winter Park (Historic Core & Vias): The premier address for pedestrian walkability along Park Avenue. Offers high cultural density, boutique shopping, and historic preservation. Review our guide to Winter Park luxury real estate.
- Windermere & The Butler Chain: Allows homeowners to downsize square footage while retaining private boat slips or community ramp access to the 11 interconnected lakes. Learn more in our Windermere luxury real estate guide.
- Baldwin Park: Delivers a New Urbanist town-center layout with single-story villas, rear-entry alley garages, and non-motorized urban lake running trails.
Five Transaction Pitfalls That Derail Downsizing Moves
- Anchoring to Peak 2022 Valuation Comps: Mispricing a legacy home based on outdated market peaks increases Days on Market and diminishes buyer leverage.
- Failing to Structure Simultaneous Buy-Sell Contingencies: Attempting to buy before selling without modeling bridge financing or lease-back terms can force double mortgages.
- Overlooking Condominium SIRS Reserves: Under Florida Senate Bill 4-D, condominium associations with underfunded structural reserve studies are flagged by lenders as non-warrantable, freezing conventional mortgage approvals.
- Ignoring 15-Year Roof Insurance Rules: Voluntarily admitted carriers in Florida often decline coverage on asphalt roofs older than 15 years, requiring seller replacements or credits during inspection periods.
- Missing the Homestead Portability Window: Florida homeowners have up to three tax years from January 1 of the abandonment year to port accumulated Save Our Homes cap benefits. Failing to file Form DR-501T triggers unnecessary tax step-ups.
Model Your Net Proceeds & Carrying Costs
Considering downsizing or rightsizing in Southwest Orlando? Connect with Yousef Zeidan for an address-specific equity model, Save Our Homes portability calculation, and a discreet assessment of off-market single-story villas.
Private Tax-Sensitive Relocation Strategy
Frequently Asked Questions About Downsizing in Orlando
Will downsizing in Orlando automatically lower my monthly living costs?
In most cases, yes, but only if you analyze monthly HOA fees, municipal millage rates, and property tax resets together. Moving from an unincorporated area like Dr. Phillips into an incorporated city with high association dues can offset expected savings if not modeled in advance.
How does Florida Homestead Portability work when downsizing to a less expensive home?
Under Florida's Save Our Homes amendment, when you downsize to a home with a lower market value, your portable tax benefit is calculated proportionally: (New Home Market Value / Old Home Market Value) multiplied by your accumulated assessment differential, up to a maximum cap of $500,000 using Form DR-501T.
Are 55+ active adult communities a good investment in Central Florida?
Active adult (55+) communities offer comprehensive lawn care, club amenities, and recreational programming. However, because future sales are restricted to age-qualified buyers, their resale pool is narrower than that of non-age-restricted luxury townhomes or single-story villas.
How do federal capital gains tax exclusions apply when selling a primary residence?
Under Section 121 of the Internal Revenue Code, married couples filing jointly can exclude up to $500,000 of capital gains from the sale of their primary residence (or up to $250,000 for single filers), provided they have owned and occupied the property as their primary home for at least two of the previous five years.
How do Senate Bill 4-D condo reserve rules impact buyers who downsize into a condominium?
Senate Bill 4-D requires condominium associations with buildings three stories or higher to complete Structural Integrity Reserve Studies (SIRS) and fully fund reserves for critical structural components. Buyers must review the association's SIRS report and reserve balance to confirm that loans are warrantable and that five-figure special assessments are not impending.
Yousef Zeidan
Luxury Right-Sizing, Downsizing, and Tax-Sensitive Relocation Specialist
Specializing in luxury right-sizing, downsizing, and tax-sensitive relocation across Dr. Phillips, Windermere, and Winter Park.
- Brokerage: RE/MAX Prime Properties
- License ID: SL3520428
- Phone: +1 (917) 743-8865
- Email: yousef@floridalistings.io
- Office Address: 311 South Main Street, Winter Garden, FL 34787, USA
Categories
Recent Posts


Request Your Confidential Risk Audit